
West Palm Beach · The Woodlands · Sheridan
Beyond the return. Into the legacy.
A private CPA advisory practice for high-income earners, founders and families. Tax, investment, estate and risk decisions, held together by one accountable advisor.
Complimentary · 40 questions · Ten minutes
The problem
Your accountant files the return. Your lawyer wrote the will. Your advisor manages the portfolio. None of them is watching the whole thing.
The space between
Each of them does good work. The risk in a high-income financial life lives in the space between them: a structure that saves tax and exposes assets, a will that no longer matches what you own, a sale planned without the liquidity to pay for it. This practice exists to stand in that space.
The approach
Five decisions that compound.
Every high-income family faces them, in this order. Get one wrong early and the cost grows every year it stays unresolved.
The framework before the transaction.
How the business earns, owns, borrows and takes on risk decides what stays protected and what becomes exposed.
How you pay yourself is a tax decision, not a payroll one.
Salary, distributions, benefits and retirement contributions, organized around the after-tax result of the business and the household.
What the business produces, and how it compounds.
Debt and equity posture, distributions, passive income, and the tax choices that keep more capital working.
The question after the founder.
Continuity, generational transfer and executive transition, decided before the founder steps away.
Whether, when, and to whom.
Counsel on the principal's side of the table, starting with whether a transaction should happen at all.
Each decision compounds on the last. Our role is to sharpen the judgment behind them before they become irreversible.
“We handle what is ours. We bring in the best specialist for what is not. And we stay responsible for the result.”
 Deen Cadi, CPAManaging Member

The Wealth Resilience Doctrine
Eight pillars hold up what you keep, protect and pass on.
The five decisions shape how wealth is built. The eight pillars decide whether it stays resilient once it exists. They have to be current together; a weakness in one puts pressure on all the rest.
Find the pillar that needs a closer lookFind your weakest pillar (opens in a new tab)Tax
What you keep from each dollar, and in which year.
Investment
What capital does after tax and inflation.
Estate
What passes, to whom, and at what cost.
Protection
What a claim can reach before it reaches the family.
Entity
Which structure holds what, and who is exposed.
Insurance
Who absorbs the loss when something goes wrong.
Liquidity
What you can turn into cash, and how quickly.
Legacy
Whether the wealth survives you.
How the work happens
A self-check. A diagnostic. Then the right treatment.
Three stages, in order. Nobody is asked to commit to the third before the first two show it is warranted.
-
Complimentary
The Wealth Resilience Assessment
Forty yes-or-no questions, five for each pillar, about ten minutes. It shows where the gaps, leaks and risks are, whether or not you ever become a client.
-
Paid planning engagement
The Wealth Resilience Blueprint
We review the returns, ownership records, accounts, policies and estate documents behind your answers. You receive a written priority map: what needs attention now, what needs a specialist, what can wait.
-
By recommendation
Ascend
If ongoing work will improve the outcome, we recommend the Ascend relationship and the scope that fits. If it won't, we say so.
Wealth Resilience Assessment
Start the Assessment (opens in a new tab)Our engagement standard
We don't accept an engagement unless the work is justified.
The value screen
the annual fee: the minimum path to value we must reasonably expect to target before we offer Ascend.
Before recommending Ascend, the Blueprint has to identify a path to value we reasonably expect to target at three times the annual fee or more: tax savings where they apply, avoided costs, better sequencing. If we can't, we don't offer the engagement.
If we can't deliver, the engagement ends.
If later review shows we can't deliver the agreed work, the engagement ends and the firm's fees for that period are returned. Automatically, without a request.
This is a screen for accepting work, not a projection of any tax, investment or financial result. It applies to the firm's own professional fees under the written engagement letter, and does not guarantee realized tax savings, investment performance, legal outcomes or results provided by third parties.
Scope of services
Three ways in. One standard of coordinated work.
Ongoing tax strategy and advisory for high-income earners and families. Ascend keeps the planning current as income, ownership, tax rules and family circumstances change.
- FoundationsEstablish the habits that protect growing income: one annual planning cycle, plus check-ins as required.
- AcceleratorPlan around income before the options close, with projections and reviews timed to your deadlines.
- CoordinatedKeep every pillar working from the same facts, with a shared timeline for every advisor.
- AdvancedRun a complex financial life with family-office discipline and quarterly strategic reviews.
These are the four Ascend Altitudes. The Blueprint recommends the one that fits, and the scope grows with the family.
 Request an introductory call
Direct access to defined fiduciary and cross-border work, for when the need is specific even if an ongoing relationship is not.
- Professional Trustee & Fiduciary ServicesIndependent, CPA-led stewardship of a trust's assets, obligations and beneficiaries. Families may keep their existing advisors.
- Global Wealth & Tax CoordinationFor families whose residence, assets, entities or beneficiaries cross jurisdictions: reporting, ownership mapping and cross-border succession.
- Counsel: The Family Office AdvisorBy invitation only. Direct private advisory when one person needs to hold every decision together.
 Make a Private Office inquiry
For founders who need the financial executive inside the business, or a principal-side advisor for one transaction.
- The Executive SeatAn embedded fractional CFO: cash-flow modeling, KPI reporting, entity and tax structure, exit and succession planning. Monthly retainer with a performance incentive.
- Deal-Based AdvisorOne sale, acquisition, capital raise or restructuring: structuring and tax planning, diligence support and negotiation. Success fee, no retainer.
All engagements are bespoke. Structure and compensation are settled in the first conversation, and only if a seat is open.
 Request this seat
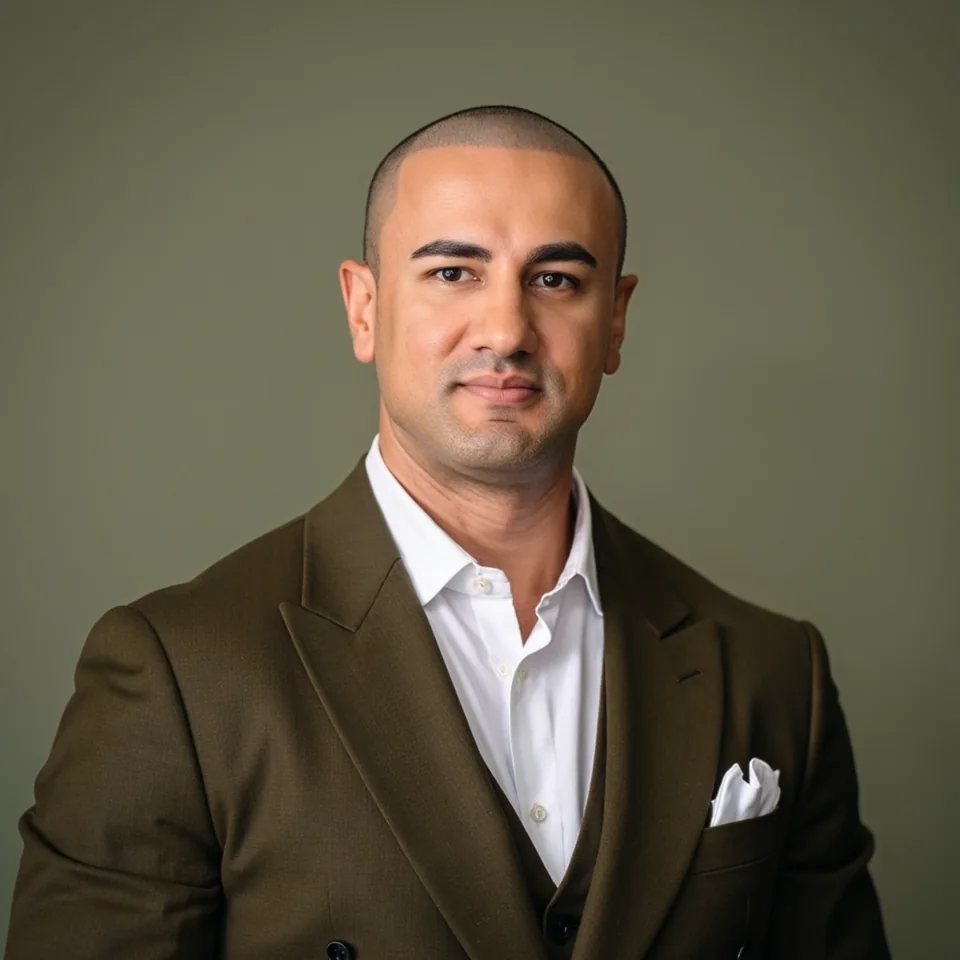
Why I built this firm
The playbook was never secret. It was just never offered to you.
I spent more than a decade beside the family offices that run the money for billion-dollar families. Those families don't have better luck or secret investments. They have a way of working: one plan, one team that actually talks, one person responsible for the whole picture.
I grew up in a family that did everything right and did it alone. My father was an accountant; my mother ran her own business. This firm exists so that playbook belongs to families like mine.
- CPA licensed in Florida, Texas, Massachusetts and Wyoming
- MSc, Law & Accounting, London School of Economics
- 20+ years in tax advisory, investment management and corporate finance
- Managing Member, Deen Cadi CPA, PLLC
 Deen Cadi, CPA
In their words
The first call before the board.
Before having conversations with my board, my counsel, or my executive team, I first speak to Deen.
When there's uncertainty, Deen steps in and takes ownership. He restores structure, brings accountability, and instills confidence. The right person in the right seat changes everything.
Questions
Before the first conversation.
Not sure where to start? The Assessment costs nothing and takes about ten minutes. Prefer to talk first? Request a 20-minute introductory call.
Request a callYes. It is complimentary, confidential and educational: forty yes-or-no questions, about ten minutes, with a resilience profile at the end. It is a self-check, not advice.
Yes, it is the paid diagnostic stage. We review the returns, ownership records, accounts, policies and estate documents behind your Assessment answers, and deliver a written priority map and order of action.
No. The firm handles what is its own and brings in the best specialist for what is not. Families often keep the advisors they trust; the work is making those advisors agree with one another.
Ongoing tax strategy and compliance are part of Ascend, with tax managed across the whole year rather than reported once.
Not directly. Audit, review and compilation work is coordinated through partner CPA firms authorized to perform it.
Deen Cadi is a CPA licensed in Florida, Texas, Massachusetts and Wyoming. The practice works from West Palm Beach, The Woodlands and Sheridan.
Ascend scope and fee are recommended after the Blueprint, never chosen from a menu in advance. The Executive Seat runs on a retainer with an incentive; Deal-Based work is a success fee with no retainer.
The client services team, in a 20-minute introductory call. It is a conversation about your circumstances and the right next step, not an advisory meeting and not individual tax, investment, legal or financial advice.
Write to team@deencadi.cpa. The firm confirms its involvement in any engagement or partnership only from that address.

Deliberate capacity
Capacity is protected, so the work gets the attention it requires.
We keep a limited number of active client seats in each scope of service. Availability is reviewed before an introductory call is confirmed.
- Length20-minute conversation
- WithThe client services team
- FormatPrivate, confidential, by appointment
A client-services conversation, not advisory and not individual tax, investment, legal or financial advice. Prefer email? team@deencadi.cpa